
Octans Insurance
Guaranteed Issue Life Insurance: Coverage Without Health Questions
Guaranteed issue life insurance is a type of permanent life insurance designed for eligible applicants who want coverage without a medical exam or health questions. It can provide an option when health conditions make traditionally underwritten coverage difficult to obtain.
- No medical exam
- No health questions for eligibility
- Permanent life insurance protection
- Graded death benefit provisions commonly apply
- Guaranteed issue life insurance accepts every applicant within the age range, with no health questions or exam.
- Most policies have a two-year graded benefit: natural-cause deaths in that window return premiums plus interest.
- Typical issue ages are 45 to 85 and coverage amounts are $2,000 to $25,000.
- If you can answer health questions, simplified issue final expense is usually cheaper and pays in full sooner.
Table of Contents

What Is Guaranteed Issue Life Insurance?
Guaranteed issue life insurance is permanent life insurance that generally does not require a medical examination or health questions for eligibility. Applicants must still satisfy the insurer’s product requirements, such as eligible issue ages and state availability.
Because the insurer accepts eligible applicants without traditional health underwriting, guaranteed issue policies commonly use smaller coverage amounts and a graded or limited death benefit during an initial policy period for non-accidental death.
How Does Guaranteed Issue Life Insurance Work?
- Confirm eligibility. Issue ages, coverage amounts, and state availability vary by carrier and product.
- Select a coverage amount. Guaranteed issue policies are commonly used for final expenses and other smaller financial obligations.
- Apply without medical underwriting. A medical exam and health questions generally are not required for eligibility.
- Review the graded benefit. Understand what the policy pays during the initial limited-benefit period and when the full death benefit becomes available.
- Maintain the policy. Pay required premiums and follow the policy contract to keep coverage in force.
Guaranteed Issue vs. Simplified Issue Life Insurance
| Feature | Guaranteed Issue | Simplified Issue |
|---|---|---|
| Medical exam | Generally not required | Often not required |
| Health questions | Generally none for eligibility | Usually required |
| Health underwriting | Generally none for eligibility | Carrier underwriting applies |
| Initial benefit | Often graded or limited for non-accidental death | May provide full coverage from issue depending on approval and contract |
What Is a Graded Death Benefit?
A graded death benefit limits the amount payable for certain causes of death during an initial period specified in the policy. The exact period and benefit schedule depend on the carrier and contract.
For non-accidental death during the graded period, a policy may provide a return of premiums paid plus an amount specified by the contract rather than the full face amount. Accidental death may be treated differently. After the graded period has been satisfied, the full applicable death benefit is generally available for a covered claim, subject to the policy terms.
Who May Consider Guaranteed Issue Life Insurance?
Guaranteed issue coverage may be considered by people who have significant health conditions, have been declined for traditionally underwritten life insurance, or prefer a product without health questions. It is often used when the primary goal is leaving funds for funeral costs, final expenses, smaller debts, or other end-of-life obligations.
It should not automatically be the first option for every applicant. Someone who can qualify for simplified-issue or traditionally underwritten coverage may have access to different premiums, coverage amounts, or benefit structures.
How Much Guaranteed Issue Coverage Do You Need?
Consider funeral or cremation costs, outstanding bills, smaller debts, existing savings, existing life insurance, and the amount you want to leave to beneficiaries. Coverage amounts available under guaranteed issue products may be limited, so the policy should be evaluated in the context of your overall protection needs.
Guaranteed Issue Life Insurance Carriers
Octans Insurance works with multiple life insurance carriers, and available guaranteed issue products depend on state, age, and carrier requirements. Gerber Life is one carrier known for guaranteed issue life insurance, and other options may be available depending on eligibility and location.
Product features, issue ages, maximum coverage, premiums, graded benefit periods, and state availability can differ substantially among insurers. Comparing the actual policy provisions is important.
Gerber Life trademark notice: Gerber Life Insurance is a trademark. Used under license from Société des Produits Nestlé S.A. and Gerber Products Company.
Common Guaranteed Issue Life Insurance Mistakes
Assuming Guaranteed Issue Means Full Immediate Coverage
Guaranteed acceptance for eligible applicants does not necessarily mean the full death benefit applies immediately to every cause of death. Review the graded benefit provisions.
Skipping Other Coverage Options
Applicants who can qualify for simplified or traditionally underwritten insurance may have additional choices. Comparing available options can help clarify the differences.
Ignoring the Policy’s Issue Ages and Limits
Guaranteed issue products have eligibility rules. Issue ages, face amounts, and state availability vary by carrier.
Focusing Only on the Monthly Premium
Review the death benefit, graded period, policy guarantees, premium requirements, and long-term affordability—not only the initial premium.
COMPARE LIFE INSURANCE OPTIONS
Guaranteed Issue Life Insurance Rates: Sample Monthly Premiums
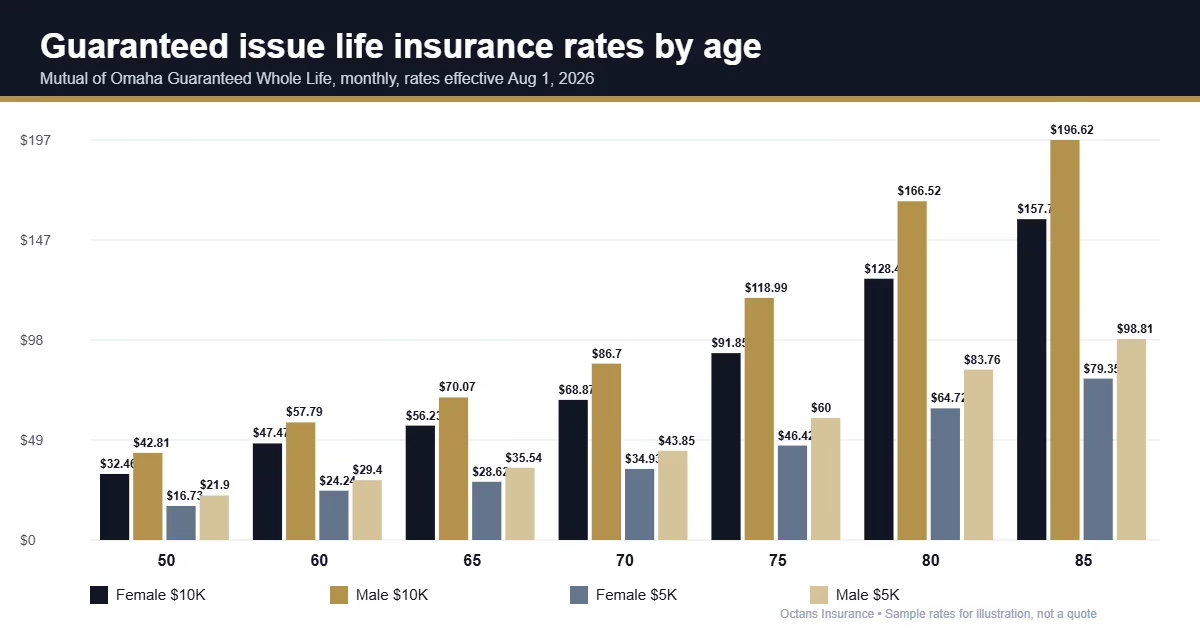
Guaranteed issue life insurance rates are higher than simplified issue rates because the carrier asks no health questions. This sample table comes directly from Mutual of Omaha’s Guaranteed Whole Life rate chart.
| Age | $5K Male | $5K Female | $10K Male | $10K Female | $15K Male | $15K Female |
|---|---|---|---|---|---|---|
| 50 | $21.90 | $16.73 | $42.81 | $32.46 | $63.71 | $48.19 |
| 60 | $29.40 | $24.24 | $57.79 | $47.47 | $86.19 | $70.71 |
| 65 | $35.54 | $28.62 | $70.07 | $56.23 | $104.61 | $83.85 |
| 70 | $43.85 | $34.93 | $86.70 | $68.87 | $129.55 | $102.80 |
| 75 | $60.00 | $46.42 | $118.99 | $91.85 | $177.99 | $137.27 |
| 80 | $83.76 | $64.72 | $166.52 | $128.44 | $249.27 | $192.16 |
| 85 | $98.81 | $79.35 | $196.62 | $157.70 | $294.42 | $236.05 |
Mutual of Omaha Guaranteed Whole Life rate chart, rates effective August 1, 2026 (issue ages 45–85, $2,000–$25,000; 50–75 in NY). Shown for illustration only; not a quote.
How Does the Two-Year Graded Benefit Work?
Guaranteed issue policies include a waiting period, usually two years. If the insured dies of natural causes during that period, the beneficiary typically receives the premiums paid plus interest (Mutual of Omaha pays 110% of premiums) instead of the full death benefit. Accidental death is generally covered in full from day one.

Coverage With Health Conditions
What Are the Drawbacks of Guaranteed Issue Life Insurance?
Guaranteed issue life insurance solves one problem: it accepts you without health questions. That ease has a price. Before you buy, weigh these five trade-offs.
- Higher cost per dollar of coverage. The insurer can’t screen out serious illness, so every buyer pays as if the group is less healthy. A healthy 65-year-old usually pays less for the same amount through simplified issue.
- Small face amounts. Most individual guaranteed issue policies stop at $25,000. Mutual of Omaha, for example, issues $2,000 to $25,000 per person.
- A two-year graded period. If death from illness happens in the first two years, the policy usually refunds premiums plus a set amount (often 10%) instead of the full benefit. Accidental death is generally paid in full from day one.
- Age windows. Applications are typically accepted only from about age 45 or 50 to 80 or 85.
- Premiums can pass the benefit. If you live a long time, you may pay in more than the policy pays out (see the math below).
Can You Get $100,000 of Guaranteed Issue Life Insurance?
Not as an individual policy, in most cases. Individual guaranteed issue life insurance is built for final expenses, so limits of $25,000 are common. Simplified and guaranteed products typically top out between $25,000 and $40,000.
There are two places larger amounts can show up:
- Employer group life. Many workplace plans offer a “guaranteed issue amount” you can elect without health questions when you first become eligible. It is often a multiple of salary. This coverage usually ends or must be converted when you leave the job.
- Simplified issue. If you can answer a short health questionnaire, simplified issue whole life or term can reach $40,000 or more, with no exam, and often with full coverage from day one.
If you need $100,000 or more, a licensed agent will usually start with a simplified or fully underwritten policy and use guaranteed issue only as a backstop.
Guaranteed Issue Life Insurance Cost vs. Benefit: A Worked Example
Here is how long it takes to pay in as much as the policy pays out. The figures use Mutual of Omaha’s published guaranteed whole life rates for a $10,000 policy (rate chart effective August 1, 2026). They are samples, not a quote.
| Buyer | Monthly premium | Yearly premium | Years until premiums equal $10,000 |
|---|---|---|---|
| Woman, age 65 | $56.23 | $675 | About 14.8 years |
| Man, age 70 | $86.70 | $1,040 | About 9.6 years |
| Woman, age 75 | $91.85 | $1,102 | About 9.1 years |
| Man, age 80 | $166.52 | $1,998 | About 5 years |
What this tells you: guaranteed issue life insurance makes the most sense when you can’t qualify for anything else, or when you expect the coverage to be needed within the next decade. If you are in good health, compare simplified issue first. It may give you more coverage for the same monthly cost.
Is Guaranteed Issue Life Insurance Worth It?
It can be. It depends on your health and your other options. Use this quick check.
- Likely worth it if you were declined for other coverage, have a serious condition such as recent cancer treatment, kidney dialysis or oxygen use, or are in a nursing home. It is also likely worth it if your family would struggle to pay $8,000 to $12,000 for a funeral.
- Maybe if you have conditions that are controlled with medication, such as diabetes or high blood pressure. Many simplified issue carriers accept these, so get both quotes.
- Probably not if you are healthy, need more than $25,000, or already have enough savings to cover final expenses.
An independent agent can quote several guaranteed issue and simplified issue carriers side by side. That shows you whether you’re paying extra for a guarantee you don’t need.
How to Apply for Guaranteed Issue Life Insurance
- Confirm your age and state. Each carrier sets its own issue ages, and some products aren’t sold in every state.
- Pick a face amount. Add up funeral costs, final bills and any debt you want paid. Most buyers choose $5,000 to $25,000.
- Compare at least two carriers. Premiums for the same amount and age can differ by 20% or more.
- Name your beneficiary. Use full legal names, and add a backup (contingent) beneficiary.
- Set up automatic payments. Missing payments is the most common way these policies lapse.
- Read the policy when it arrives. You have a free-look period, usually at least 10 days depending on your state, to cancel for a full refund.
How to Keep Your Guaranteed Issue Policy Active
Guaranteed issue life insurance is permanent only if premiums keep getting paid. Most policies include a grace period, often 31 days, after a missed payment. If the premium isn’t paid by then, the policy can lapse. If that happens, buying again means a new two-year graded period at an older, higher rate. Tell your beneficiary where the policy is kept, and give a trusted family member permission to receive late-payment notices if your carrier offers that option.
Guaranteed Issue vs. Final Expense Insurance
These terms overlap, but they aren’t the same. “Final expense insurance” describes the purpose: a small whole life policy meant to pay for a funeral and last bills. “Guaranteed issue” describes how you get approved: no health questions. Some final expense policies are guaranteed issue, but many are simplified issue and ask a few health questions in exchange for full coverage from day one and lower rates. If you can answer “no” to the health questions, a simplified final expense policy is usually the better buy. Learn more on our final expense insurance page.
Guaranteed Issue Life Insurance FAQs
Does guaranteed issue life insurance require a medical exam?
Generally, no medical examination is required for eligibility, although applicants must meet the product’s other eligibility requirements.
Are there health questions?
Guaranteed issue products generally do not use health questions to determine eligibility. Product rules vary, so review the specific application and contract.
Can I be declined for guaranteed issue life insurance?
Guaranteed issue refers to acceptance without health-based underwriting for applicants who satisfy the product’s eligibility requirements. Age, state availability, and other product requirements still apply.
Does guaranteed issue coverage have a waiting period?
Many guaranteed issue policies use a graded or limited death benefit for non-accidental death during an initial period. The exact provisions vary by policy.
What happens if death occurs during the graded period?
The benefit depends on the policy and cause of death. For non-accidental death, some contracts provide a return of premiums plus an additional amount specified in the policy rather than the full face amount.
Is guaranteed issue life insurance permanent?
Guaranteed issue life insurance is commonly structured as whole life insurance and is designed as permanent coverage when required premiums are paid and policy requirements are satisfied.
Can guaranteed issue insurance be used for funeral expenses?
Yes. Beneficiaries may use life insurance proceeds for funeral or burial costs and other financial needs, subject to applicable law and policy circumstances.
Should I choose guaranteed issue if I have health problems?
It can be one option, but health problems do not automatically mean guaranteed issue is the only available coverage. Comparing available products and underwriting requirements can identify the options for which an applicant may be eligible.
Compare Guaranteed Issue Life Insurance with Octans Insurance
Octans Insurance is an independent insurance agency. We help consumers compare life insurance options from multiple carriers and understand differences in underwriting, graded benefits, premiums, coverage amounts, and eligibility.
Use our Easy Quote Tool, learn more about Octans Insurance, review Final Expense Insurance, or learn about Whole Life Insurance.
Related Coverage and Guides
- See if you qualify for life insurance
- Colonial Penn life insurance review
- Final expense insurance
- Gerber Life guaranteed issue
- Life insurance for seniors
- Deaths not covered by life insurance
Sources: Mutual of Omaha Guaranteed Whole Life rate chart (effective Aug 1, 2026); Choice Mutual, Guaranteed Issue Life Insurance (updated June 8, 2026).
Important: Octans Insurance agents are licensed in the states in which they operate. Coverage availability and rates may vary by state. Premium estimates, when provided, are for illustrative purposes only. Final rates are determined by the insurance carrier based on applicable product and underwriting criteria. Policy terms, exclusions, limitations, graded benefit periods, riders, issue ages, and availability vary by carrier and state.
Ready to Compare Guaranteed Issue Life Insurance?
Review available life insurance options based on your needs, age, budget, and eligibility.
GET YOUR FREE LIFE INSURANCE QUOTE
(617) 935-9220 | life@octansinsurance.com