Mortgage Protection Insurance Scam? How to Read Mailers
Mortgage Protection Insurance Scam? How to Read Mailers: The Short Answer
Usually it isn’t a scam: mortgage protection is real life insurance, and lenders generally can’t require it. But the letters can look like lender notices. Some come from companies that aren’t your lender, using public loan records or credit bureau lists. Verify the sender using your mortgage statement, not the letter.
- Mortgage protection is legal life insurance; the sales letters are the part to read carefully.
- Check the fine print for ‘not affiliated with’ your lender or ‘public records’ language.
- Call your servicer using the number on your monthly statement, never the number in the letter.
- Compare with a level term policy you own, and opt out of prescreened offers to reduce mail.
Table of Contents
Make sure your family is financially protected today!
Worried about a mortgage protection insurance scam? Usually the product is real life insurance, but the letters selling it can look like they came from your lender. Some come from companies that aren’t your lender, using public loan records or credit bureau lists. Lenders generally can’t require you to buy it. Here is how to read the mail.
Why new homeowners get mortgage protection mail
Soon after closing, many buyers start getting mortgage protection letters: envelopes with their lender’s name, their loan amount and words like “important” or “final notice.” There are two well-documented ways marketers find you.
Public records. Loan details can be gathered from government records. Louisiana’s R.S. 6:412.1 shows how common this is. It lets a company that is not your lender use publicly available loan information from federal, state or local government records only if the solicitation says the information was retrieved from public records and that the sender is not affiliated with the lender. Those statements must appear on the front page in bold type.
Credit bureau lists. According to the Federal Trade Commission, companies can set criteria and ask a credit bureau for a list of people who meet them. These “prescreened” offers can be for credit or insurance.
We can’t tell which source a given letter used. But either way, the sender may have no connection to the company that holds your mortgage.

Is mortgage protection insurance a scam?
It depends on what you mean by “scam.” If you are asking whether mortgage protection insurance is legit, the product itself is legal insurance. As our mortgage protection insurance guide explains, the term describes a purpose more than one product. A family can use term or permanent life insurance to pay off a mortgage if a borrower dies.
Traditional lender-tied coverage has trade-offs. On the plus side, it often has limited or no medical underwriting, so it can be easier to get. On the other hand, the benefit often shrinks as the loan is paid down, and the money often goes to the lender. The National Association of Insurance Commissioners (NAIC) says credit life proceeds are paid directly to the creditor.
The real problem is the sales method. A letter that looks like a bill or a lender notice can push people to act fast. And a true mortgage protection insurance scam, run by an impostor, is possible too. The FTC says scammers often pretend to be from a business you know or a government agency.

How to tell a sales mailer from a lender notice
A notice from your loan servicer is about your account. A sales mailer is about selling you something. These signs help you sort them:
| What you see | Likely a sales mailer | Likely from your servicer |
|---|---|---|
| Sender name | A company name you don’t recognize, or your lender’s name only in the body text | The same servicer name that appears on your monthly statement |
| Fine print | Says “not affiliated with” your lender, or that details came from public records | No such disclaimer |
| Your information | Loan amount and lender name, but no account number | Your loan account number and payment details |
| Request | Call to “complete your file” or “activate” coverage | Payment, escrow or account servicing items |
| Phone number | A number that doesn’t match your statement | Matches the number on your statement |
When in doubt, follow the FTC’s advice. Contact the organization using a phone number, website or email address you know is real. For a mortgage, that is the number on your monthly statement, not the one in the letter.
Red flags of a mortgage protection insurance scam
Watch for these warning signs in calls and letters:
- Words like “final notice” or “urgent” on the first letter you have ever received from the sender.
- Claims that your lender requires the coverage. The NAIC says that, except for private mortgage insurance (PMI), lenders cannot deny you credit if you don’t buy optional credit insurance.
- A caller who won’t give a name, company and license number. The Wisconsin Office of the Commissioner of Insurance advises asking for the caller’s name and the company the caller represents when you’re solicited by phone.
- Requests for your Social Security number or bank details before you have seen any written policy terms.
- Pressure to pay now, or requests to send money, cryptocurrency or gold. The FTC says never to send these to someone you don’t know.
- Vague answers about who receives the death benefit or whether it shrinks over time.
Questions to ask before you buy
If you are interested in coverage, slow down and ask. The NAIC’s credit insurance guide suggests the first five questions below, and they work for any policy tied to a loan. The last two are our additions for mortgage protection offers:
- How much is the premium?
- Will the coverage last the full length of the loan and cover the full amount?
- Is there a waiting period before coverage starts?
- What are the limits and exclusions?
- Can I cancel, and what refund is available?
- Does the benefit go down as the balance goes down?
- Who is the beneficiary: the lender or my family?
Also ask for the agent’s license number and check it. The NAIC’s life insurance page says your state department of insurance provides a list of agents and companies licensed in your state.
Mortgage protection vs a regular term policy
The NAIC suggests checking what a traditional term life policy would cost before buying credit insurance. Here is how the two usually compare, based on our mortgage protection guide:
| Feature | Traditional mortgage protection | Level term life you own |
|---|---|---|
| Death benefit | Usually decreases as the loan is paid down | Stays level for the term |
| Who gets paid | Often the lender | Your named beneficiary, who decides how to use it |
| If you refinance or sell | Lender-tied coverage often ends | Generally stays in force, subject to its terms |
| Underwriting | Often limited or none | Health questions, database checks, sometimes an exam |
For example, our guide shows a published sample rate of $28 a month for a 40-year-old woman buying $250,000 of 20-year term (non-smoker in average health, as of October 2026). That is $336 a year ($28 times 12). It is a sample, not a quote. With level term, the benefit stays $250,000 even as the mortgage balance falls, and her family keeps anything left after paying off the loan.
Mortgage protection may still fit someone who has trouble qualifying for regular term coverage. It is a trade-off, not a trap.

How to cut down on mailers and calls
If you want to stop mortgage protection mailers and calls, you can reduce the flow, though no single step stops it all.
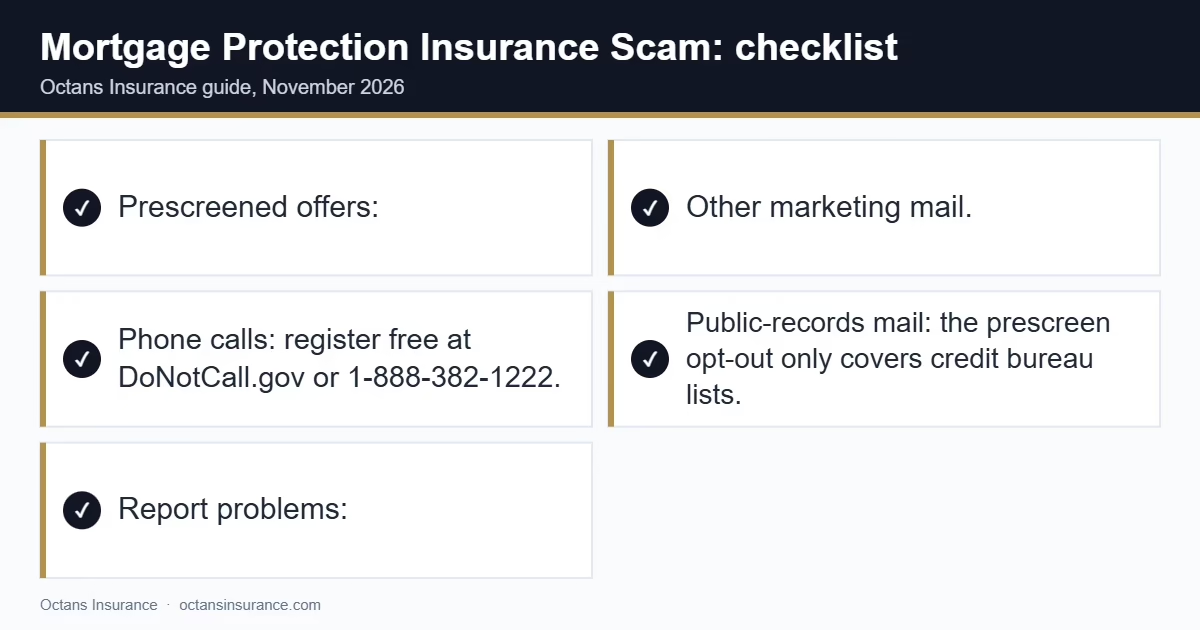
- Prescreened offers: the FTC says you can opt out for five years at optoutprescreen.com or 1-888-5-OPT-OUT (1-888-567-8688), or permanently by signing and returning a form. Requests are processed within five days, but offers may continue for several weeks.
- Other marketing mail: the FTC’s junk mail guide says DMAchoice.org registration costs $6 online and lasts 10 years; registering by mail costs $7.
- Phone calls: register free at DoNotCall.gov or 1-888-382-1222. The FTC says registration never expires, though sales calls may continue for up to 31 days. Companies you recently did business with can still call, but must stop if you ask.
- Public-records mail: the prescreen opt-out only covers credit bureau lists. Contact other senders directly and ask to be removed.
- Report problems: report impostors at ReportFraud.ftc.gov, and report insurance sales concerns to your state insurance department.
To compare options calmly, read our guides to term life insurance, term vs whole life and no-exam life insurance. Our how much life insurance do I need guide can help you size coverage to your mortgage and other debts.
Keep Reading: Related Guides
- Mortgage protection insurance guide
- Term life insurance
- Term vs whole life insurance
- How much life insurance do I need?
- Denied Life Insurance? 7 Steps to Take Next
- Life Insurance Phone Interview
Mortgage Protection Insurance Scam? How to Read Mailers: Frequently Asked Questions
Why am I getting mortgage protection letters?
Marketers can find new homeowners in two documented ways. Loan details can come from public government records, and Louisiana law, for example, requires such mail to say the information came from public records and that the sender isn’t affiliated with your lender. Companies can also buy prescreened lists from credit bureaus for credit or insurance offers, according to the FTC.
Is mortgage protection insurance legit?
The product is legal insurance. It is life insurance meant to help pay off a mortgage if a borrower dies. Traditional versions often have a benefit that shrinks as the loan is paid down and may pay the lender, while a level term policy you own pays your beneficiary. The mailers are the part to be careful with. Verify the sender and the agent’s license before you share any information.
Does my lender require mortgage protection insurance?
Generally, no. The NAIC says that, except for private mortgage insurance (PMI), lenders cannot deny you credit if you don’t buy optional credit insurance. Wisconsin’s insurance regulator says lenders cannot require credit life insurance. If a letter or caller says coverage is required, call your servicer using the number on your monthly statement to check.
How do I stop mortgage protection mailers?
Opt out of prescreened credit and insurance offers at optoutprescreen.com or 1-888-5-OPT-OUT (1-888-567-8688), for five years or permanently. Register with DMAchoice.org ($6 online, lasts 10 years) for other marketing mail, and put your number on the free Do Not Call Registry. Mail based on public records may continue, so ask those senders directly to remove you.
Is mortgage protection the same as PMI?
No. According to the NAIC’s consumer guide to home insurance, lenders usually require private mortgage insurance (PMI) if your down payment is less than 20% of the home’s price, and PMI protects the lender if you default on your mortgage. Mortgage protection is optional life insurance that pays if a borrower dies. The NAIC also says that, except for PMI, lenders cannot deny you credit if you don’t buy optional credit insurance.
This article is general information, not legal, tax, or medical advice. Premium examples are published samples, not quotes.
About examples and tools: Hypothetical examples, sample rates, calculators and quizzes on this site are for general educational and illustrative purposes only. They are not quotes, offers of coverage, or guarantees of eligibility, approval, price or benefits, and they are not legal, tax, financial or medical advice. The insurance company decides eligibility and price; Medicare rules are set by CMS and the Social Security Administration.