
Coverage Calculator
How Much Life Insurance Do I Need? A Simple Calculator Guide
How much life insurance do I need? For most families, the answer is 10 to 15 times annual income, adjusted for debts, the mortgage, education goals, and savings. This guide walks through three quick methods and a step-by-step calculation.
- Start with 10 to 15 times the income your family relies on.
- Add debts, the mortgage, education, and final expenses.
- Subtract savings and existing coverage.
- Seniors often need only final expense coverage.
Table of Contents
How Much Life Insurance Do I Need? Three Quick Methods
| Method | How it works | Example: $70,000 income |
|---|---|---|
| Income multiple | 10 to 15 times annual income | $700,000 to $1,050,000 |
| DIME method | Debt + Income years + Mortgage + Education | $40K debt + $700K income + $250K mortgage + $100K education = $1,090,000 |
| Needs analysis | Total future needs minus existing assets and coverage | Varies; often the most accurate |


How to Calculate Your Life Insurance Needs Step by Step
- Income replacement: multiply the income your family relies on by the number of years they would need it.
- Debts: add the mortgage balance, car loans, credit cards, and student loans.
- Future goals: add college costs and childcare.
- Final expenses: add $10,000 to $15,000 for funeral costs and final bills.
- Subtract resources: savings, retirement accounts your family could use, and existing life insurance, including employer coverage.
How Much Life Insurance Do Seniors Need?
Many retirees no longer need income replacement. Their life insurance needs focus on funeral costs, final medical bills, any remaining mortgage, and protecting a spouse who would lose part of a pension or Social Security income. A $10,000 to $25,000 final expense policy covers the first need for most families.
What Are Common Mistakes When Choosing a Coverage Amount?
- Relying only on employer coverage, which often ends when you change jobs.
- Forgetting a stay-at-home parent, whose childcare and household work would be costly to replace.
- Choosing a term too short for the youngest child or the mortgage.
- Never reviewing coverage after a marriage, birth, or new home.
Source: NAIC consumer guide to life insurance.
How Much Life Insurance Do I Need at Each Age?
Your needs change as debts shrink and savings grow. These ranges are common starting points before a full needs analysis.
| Age range | Typical coverage goal | Common policy |
|---|---|---|
| 20s to 30s with children | 10 to 15 times income | 20 or 30-year term |
| 40s | Remaining mortgage plus 10 years of income | 15 or 20-year term |
| 50s to early 60s | Remaining debts plus final expenses | 10-year term or whole life |
| Retirement | Final expenses of $10,000 to $25,000 | Final expense whole life |
Why do coverage rules of thumb disagree?
You will see different answers to the same question. Some guides say 10 to 15 times your income. The NAIC consumer guide to life insurance notes that some experts suggest five to eight times your current income. That is a big range.
The reason is simple. A multiple of income does not know your life. It does not know if you rent or own, how old your kids are, or how much you have saved. Two people who earn the same can need very different amounts.
That is why the NAIC recommends working through your actual needs rather than relying on a multiple. It lists the things to weigh:
- The income you provide that your family would lose
- How many people depend on you, and for how long
- Final expenses, such as medical and burial costs
- Debts you would leave behind
- Possible estate taxes
- Inflation, which makes a fixed dollar amount worth less over time
Use a multiple as a quick starting point. Then test it against these real costs. The worked example below shows how.
It also helps to be honest about what you want the money to do. Some families only want the mortgage gone. Others want to keep the same lifestyle until the kids are grown, plus pay for college. Both are fair goals, but they lead to very different numbers. Write your goal down first, then size the policy to match it.
If you are still asking “how much life insurance do I need?” after running the numbers, pick the higher figure when the price difference is small. The cost table further down shows why that is often the case.
A worked example: how much life insurance do I need?
This is a hypothetical example. The family and every number in it are made up to show the math. Plug in your own figures.
Meet a 40-year-old parent who earns $70,000 a year. They have two children, ages 6 and 9, a $250,000 mortgage, $50,000 in savings, and life insurance at work equal to one year of pay.
| Item | Amount | Notes |
|---|---|---|
| Replace income for 12 years | +$840,000 | Until the youngest turns 18 |
| Pay off the mortgage | +$250,000 | Current balance |
| College goal | +$100,000 | $50,000 per child |
| Funeral | +$8,300 | NFDA 2023 national median, viewing and burial |
| Savings | -$50,000 | Cash the family could use |
| Work life insurance | -$70,000 | Only if the job is kept |
| Estimated need | $1,078,300 | Round to about $1 million |
Notice two choices that change the answer. First, should you count the work policy? If you change jobs, it may go away. Some people leave it out to be safe, which would raise the need to about $1.15 million. Second, Social Security survivor benefits could replace part of the income, which would lower the need. The next section explains how.
In this example, the answer lands near 15 times income. A family with a smaller mortgage, older kids or more savings might land near the NAIC’s five to eight times.
Next, put a price on it. Using the MoneyGeek sample rates shown later on this page, a 40-year-old man would pay about $59 a month for $500,000 of 20-year term. Two of those policies, for $1 million in total, would run roughly $118 a month. A single $1 million policy may cost less than two smaller ones, so ask for both quotes. These are samples, not a quote, and your health and state will change the price.
Finally, choose a term length. The youngest child here is 6, and the mortgage has years to go. A 20-year term would cover both. If the budget is tight, the laddering idea further down can trim the cost while keeping the most coverage in the riskiest years.
How do Social Security survivor benefits affect your number?
If you pay into Social Security, your family may get monthly survivor benefits when you die. These can cover part of the income gap, so they can lower how much life insurance you need.
According to FedWeek’s summary of Social Security survivor rules:
- A widow or widower at full retirement age or older generally gets 100% of the worker’s basic benefit.
- A widow or widower age 60 to full retirement age gets about 71% to 99%.
- A widow or widower of any age caring for a child under 16 gets 75%.
- Children get 75% of the worker’s benefit.
- A one-time payment of $255 may go to a qualifying spouse or child.
Two cautions. First, these are percentages of your benefit, which depends on your own work record and earnings. Second, the parent’s 75% benefit is tied to caring for a child under 16. Once the children grow older, part of that support goes away. So survivor benefits tend to help most in the early years.
Here is a hypothetical example. Say your basic benefit would be $2,000 a month. A spouse caring for a 6-year-old could get about $1,500 (75%), and each child could get about $1,500 (75%), subject to Social Security’s own rules and family limits. That is real money. But it is not a full income, and it shrinks as the kids grow.
To estimate your own figures, check your Social Security statement. Then subtract a cautious estimate from the income your family would need to replace. Many families choose to count only part of it, so the plan still works if the rules or amounts change.
Is life insurance through work enough?
For many families, no. Work coverage is a good extra, but it has limits:
- It is often tied to your job. If you leave, retire or are laid off, the coverage may end. Ask HR whether your plan lets you convert or carry it with you, and what that would cost.
- The amount is set by the plan, not by your needs. In the worked example above, one year of pay covered only a small slice of the need.
- Extra coverage can raise your taxes. The IRS excludes the first $50,000 of employer group-term life from income. The cost of coverage above $50,000 is added to your taxable pay and is subject to Social Security and Medicare taxes.
A common approach is to treat work coverage as a bonus. Buy your own policy for the core need, so your family stays protected if your job changes. Then let work coverage add a cushion while you have it.
What does more coverage actually cost?
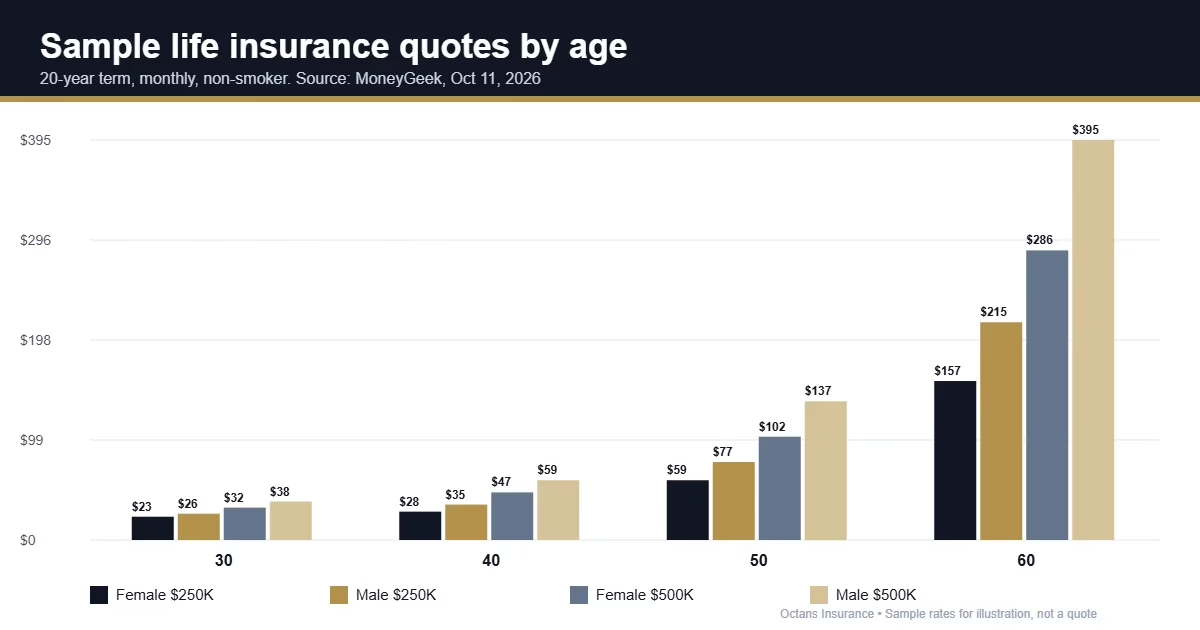
People often buy less than they need because they assume twice the coverage costs twice as much. It usually does not. The table shows sample 20-year term rates for non-smokers in average health from MoneyGeek (updated Oct. 11, 2026). Samples, not a quote.
| Age | $250,000 (F / M) | $500,000 (F / M) | Extra cost to double coverage (F / M) |
|---|---|---|---|
| 30 | $23 / $26 | $32 / $38 | +$9 (39%) / +$12 (46%) |
| 40 | $28 / $35 | $47 / $59 | +$19 (68%) / +$24 (69%) |
| 50 | $59 / $77 | $102 / $137 | +$43 (73%) / +$60 (78%) |
| 60 | $157 / $215 | $286 / $395 | +$129 (82%) / +$180 (84%) |
At 30, doubling coverage from $250,000 to $500,000 adds about $9 to $12 a month. At 40, it adds about $19 to $24. The savings from buying less are smallest when you are young, which is also when most families need the most coverage.
See more prices on our life insurance rates by age page.
How much do you need just for final expenses?
Even if you have no dependents, someone will handle your funeral and final bills. The National Funeral Directors Association’s most recent published study put the 2023 national median at $8,300 for a funeral with viewing and burial, and $6,280 for a funeral with cremation, as reported by Tribute Technology. Those medians do not include a vault, cemetery plot or headstone, so plan for more if you want burial.
You can also control the cost. Under the FTC Funeral Rule, funeral homes must give you an itemized price list. You can buy only the items you want instead of a package. A home cannot refuse a casket or urn you bought somewhere else, and it cannot charge a fee for using one.
Final bills can go beyond the funeral. Think about any unpaid medical bills, a last month of rent or utilities, and travel for family. Adding a buffer on top of the funeral cost gives your family room to breathe.
For final expenses alone, a smaller whole life policy may fit. Our small life insurance policy guide shows sample costs.
Should you split coverage into more than one policy?
The answer to “how much life insurance do I need?” changes over time. Your need is highest when your kids are young and your mortgage is large. It shrinks as debts get paid and savings grow. One way to match that is to buy two or more term policies with different lengths. This is often called laddering.
Here is a hypothetical example using the $1 million need from above:
- $500,000 on a 20-year term, to cover the years until the kids finish school
- $500,000 on a 10-year term, to cover the heaviest mortgage and childcare years
After 10 years, the shorter policy ends and your coverage drops to $500,000. That may match a smaller mortgage and older children. Whether a ladder saves money depends on the actual quotes, so compare it against a single 20-year policy before you decide.
When any policy nears its end date, review your options early. Thrivent suggests starting at least six months before the term ends. Our guide to what happens when term life insurance ends covers each choice.
Do you need extra coverage to pay taxes on the payout?
Usually not. The IRS says life insurance proceeds paid to a beneficiary because of the insured’s death are generally not included in gross income. So a $500,000 death benefit generally reaches your family as $500,000 for income tax purposes.
There is one exception to plan for. If the payout is held by the insurer and paid out over time, any interest it earns is taxable. Very large estates may also face estate taxes, which the NAIC lists as a factor in sizing coverage. If your estate is large, ask a tax or estate professional.
So when you ask how much life insurance do I need, you can usually size the policy to the real costs above without adding a tax cushion.
Life Insurance Needs FAQ
Is 10 times my income enough life insurance?
It is a reasonable starting point, but families with large mortgages, young children, or college plans often need more.
Does a stay-at-home parent need life insurance?
Yes. Replacing childcare and household work can cost tens of thousands of dollars per year.
How often should I review my coverage?
Review after any major life event and at least every few years.
Do I need life insurance if I have no dependents?
Often not much. If no one relies on your income and your debts wouldn’t pass to anyone, a small policy for final expenses may be enough. Consider more if you co-signed a loan, want to leave money to someone, or expect to start a family, since coverage costs less when you’re younger.
How much life insurance do I need for each child?
There’s no fixed rule. A simple approach is to multiply the yearly cost of raising each child by the years until they’re independent, then add any college savings goal. Our calculator steps above include this.
Related Coverage and Guides
- How life insurance secures your loved ones’ future
- Term life insurance
- Life insurance quotes
- Term vs. whole life insurance
Important: Octans Insurance agents are licensed in the states in which they operate. Coverage availability and rates may vary by state. Premium examples, when provided, are illustrative samples from published sources, not quotes. Final rates are determined by the insurance carrier based on underwriting and applicable policy criteria. Policy terms, exclusions, limitations, riders, and availability vary by carrier and state.
Ready to Compare Your Options?
Start with a free, no-obligation quote review with a licensed Octans agent.
(617) 935-9220 | life@octansinsurance.com